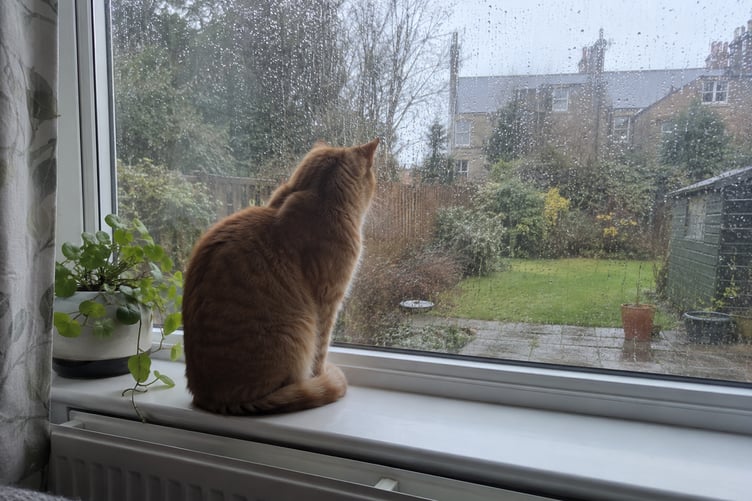
The carrier comes out of the cupboard and the cat disappears under the bed. Anyone who has tried to get a reluctant cat to the vet knows why some appointments get put off.
Cats Protection's CATS Report 2025 puts numbers on it. 57% of cat owners said they don't take their cat to the vet as often as they'd like, and for the first time the stress of the visit ranked alongside cost as a barrier, at 25% each.
For an unexpected illness or injury, insurance can take some of the worry about cost out of that decision, within the policy's excess, limits and exclusions. That's easier to judge once you know what a policy pays for and where it stops.
The bills a claim can cover
A policy that covers illness and injury pays towards treatment for problems that start after your cover begins. For a cat, that might be blood tests when she starts drinking more than usual, stitches and antibiotics for an abscess after a fight, X-rays after a road accident, an operation, a night on a drip, or the medicine that follows.
You pay the excess, a fixed amount towards each claim. Some policies add a co-payment too, a percentage of each bill you pay yourself. The insurer pays the rest, up to the limit.
How long that limit lasts depends on the type of policy. Accident-only cover pays for injuries but not illness. A time-limited policy pays for each condition for a set period, often 12 months. A maximum-benefit policy pays a fixed sum per condition and then stops. A lifetime policy resets its limit each year you renew, which matters for the long-term conditions cats often develop later, such as kidney disease or an overactive thyroid.
Routine care stays with you
Annual vaccinations, flea and worm treatment, neutering, microchipping and nail trims are usually left out. Insurance is there for the unexpected, so the predictable costs of owning a cat sit outside it.
That makes the yearly health check easy to skip, even though it can catch problems early, when they're simpler to treat. Budgeting for it separately means it doesn't compete with everything else.
Video calls and the visit you keep putting off
Some policies include video calls with a vet. For a cat who hates travelling, a call can help you decide whether a trip to the practice is needed today, can wait for a routine appointment, or isn't needed at all. You can ask about a change you've noticed, such as a cat eating less or hiding more, without the carrier coming out first.
Some signs shouldn't wait for a call. A male cat straining in the litter tray and passing little or nothing, or a cat struggling to breathe, needs to be seen in person straight away.
Cats who roam
Outdoor cats face more accidents, from traffic to fights, and some policies add extras for cats who go missing. Those extras differ a lot from one policy to the next, so read the list rather than assuming.
Insurers often ask whether your cat goes outside, because it affects the risk. If you're asked, answer accurately. A wrong answer can cause trouble with a claim later.
Commonly excluded
The Financial Ombudsman notes that most policies don't cover pre-existing conditions, or illnesses that first appear in the first 14 days of a new policy. A cat already being treated for a sensitive stomach when you bought cover would usually find that problem excluded.
Cosmetic procedures and breeding costs aren't covered either, and nor is anything on the policy's own exclusions list. Some policies limit or leave out behavioural treatment. Take a cat who starts spraying indoors: ask your vet to rule out a medical cause such as cystitis first, because that would normally be claimed as an illness rather than a behaviour problem.
An older cat with something on record
If your cat is older, start by asking whether the insurer takes on new policies at her age. Then ask how it treats past vet visits. A symptom noted by a vet, such as weight loss, can count as pre-existing even if nothing was diagnosed at the time, and a problem found later might be treated as linked to it.
That doesn't rule out cover for new problems. Read the exclusions closely and ask for anything unclear to be confirmed in writing before you buy.
Making a claim
In many cases you pay the vet, then send the insurer a claim form with the invoice, although some practices can claim on your behalf. The insurer may ask your practice for your cat's clinical history, so it helps if your cat has been registered with a vet from the start. A claim is quicker when that history is complete and the invoice shows what each charge was for.
Before you buy, read the short summary document for what a cat policy covers alongside the longer policy wording. The wording is where the insurer defines a pre-existing condition and explains when two problems count as the same condition, which matters the second time something like cystitis comes back.
Comments
We've recently changed our login process. If you have an account for commenting, you will need to re-register on the login window.
This article has no comments yet. Be the first to leave a comment.